01
Executive overview
Key findings
SAR 56 billion (USD 14.9 billion): Sharakat's public-private partnership portfolio, 48 projects of which 15 are in service (ministry statement, June 2026)
SAR 11.07 billion: private bulk water deals that reached financial close in the last quarter of 2025, the Jubail–Buraydah transmission line (SAR 8.5 billion) and Ras Mohaisen desalination plant (SAR 2.57 billion) (calculated); Sharakat has announced no financial close since 25 December 2025
USD 3.14 billion: Saudi water contract awards in H1 2026, against USD 7.58 billion in H1 2025, about 59% lower (calculated)
About USD 2 billion: the 859 km Riyadh–Qassim transmission line, at preferred bidder since December 2025 with no developer agreement signed by September 2026
02
Buyer relevance
Who the report is for
Desalination and transmission developers
Track the Riyadh–Qassim, Jubail 4&6 and 2027-wave projects by stage, bid price and target operation date before committing bid teams.
Civil, transmission and process contractors
Find construction work on the financed Jubail–Buraydah line and the sewage plants at Riyadh East, Arana, Hadda and the Riyadh Central Cluster.
Project lenders and infrastructure investors
See how recent deals were financed, including the fully Islamic SAR 8.5 billion Jubail–Buraydah syndicate, and where closes have slipped.
Operators and advisers
Size NWC's operation packages and the six-cluster concession programme, and follow the Water Transmission Company's delivery-model review.
03
Decision scope
Questions answered
How large is Sharakat's portfolio?
SAR 56 billion (USD 14.9 billion) across 48 projects, 15 of them in service, according to a ministry statement in June 2026.
Which projects are waiting for financial close?
The 859 km Riyadh–Qassim transmission line, estimated at about USD 2 billion, has had a preferred bidder since December 2025; the Arana and Hadda sewage plants, 350,000 m³ a day combined, missed their expected Q2 2026 closes.
Has the market slowed?
Contract awards fell to USD 3.14 billion in H1 2026 from USD 7.58 billion in H1 2025, about 59% lower, on MEED Projects data.
When does new desalination procurement restart?
Sharakat's next wave, about 2.8 million m³ a day across seven plants led by Shuqaiq 4, is not expected to reach its first request for proposals until early 2027.
How much does NWC build?
NWC completed 50 projects worth more than SAR 2.4 billion in H1 2026, against a SAR 102.9 billion programme earmarked in 2023.
04
Inside the report
Inside the complete report
Executive Snapshot
1. Why This Matters Now in Saudi Arabia
2. Current Position
3. Key Programmes, Projects and Investment
4. Policy, Regulation and Institutions
5. Risks and Constraints
6. Strategic Implications
7. What to Watch
Source Register
05
Public preview
What to watch next
1. Why This Matters Now in Saudi Arabia
Financial close announcements on Sharakat's news page; the first request for proposals of the 2027 desalination wave.
3. Key Programmes, Projects and Investment
Financial close on Riyadh–Qassim, Arana and Hadda; Riyadh East preferred bidder; a Jubail 4&6 purchase agreement; confirmation that Rayis–Rabigh has entered commercial operation.
4. Policy, Regulation and Institutions
WTCO's decision on the delivery model; any notice that SWA plant ownership is transferring; the effect of the 2027 tariff rates on NWC's revenue base and cost recovery.
5. Risks and Constraints
The time from preferred bidder to close on Riyadh–Qassim; the number of bids on the first 2027 desalination tender.
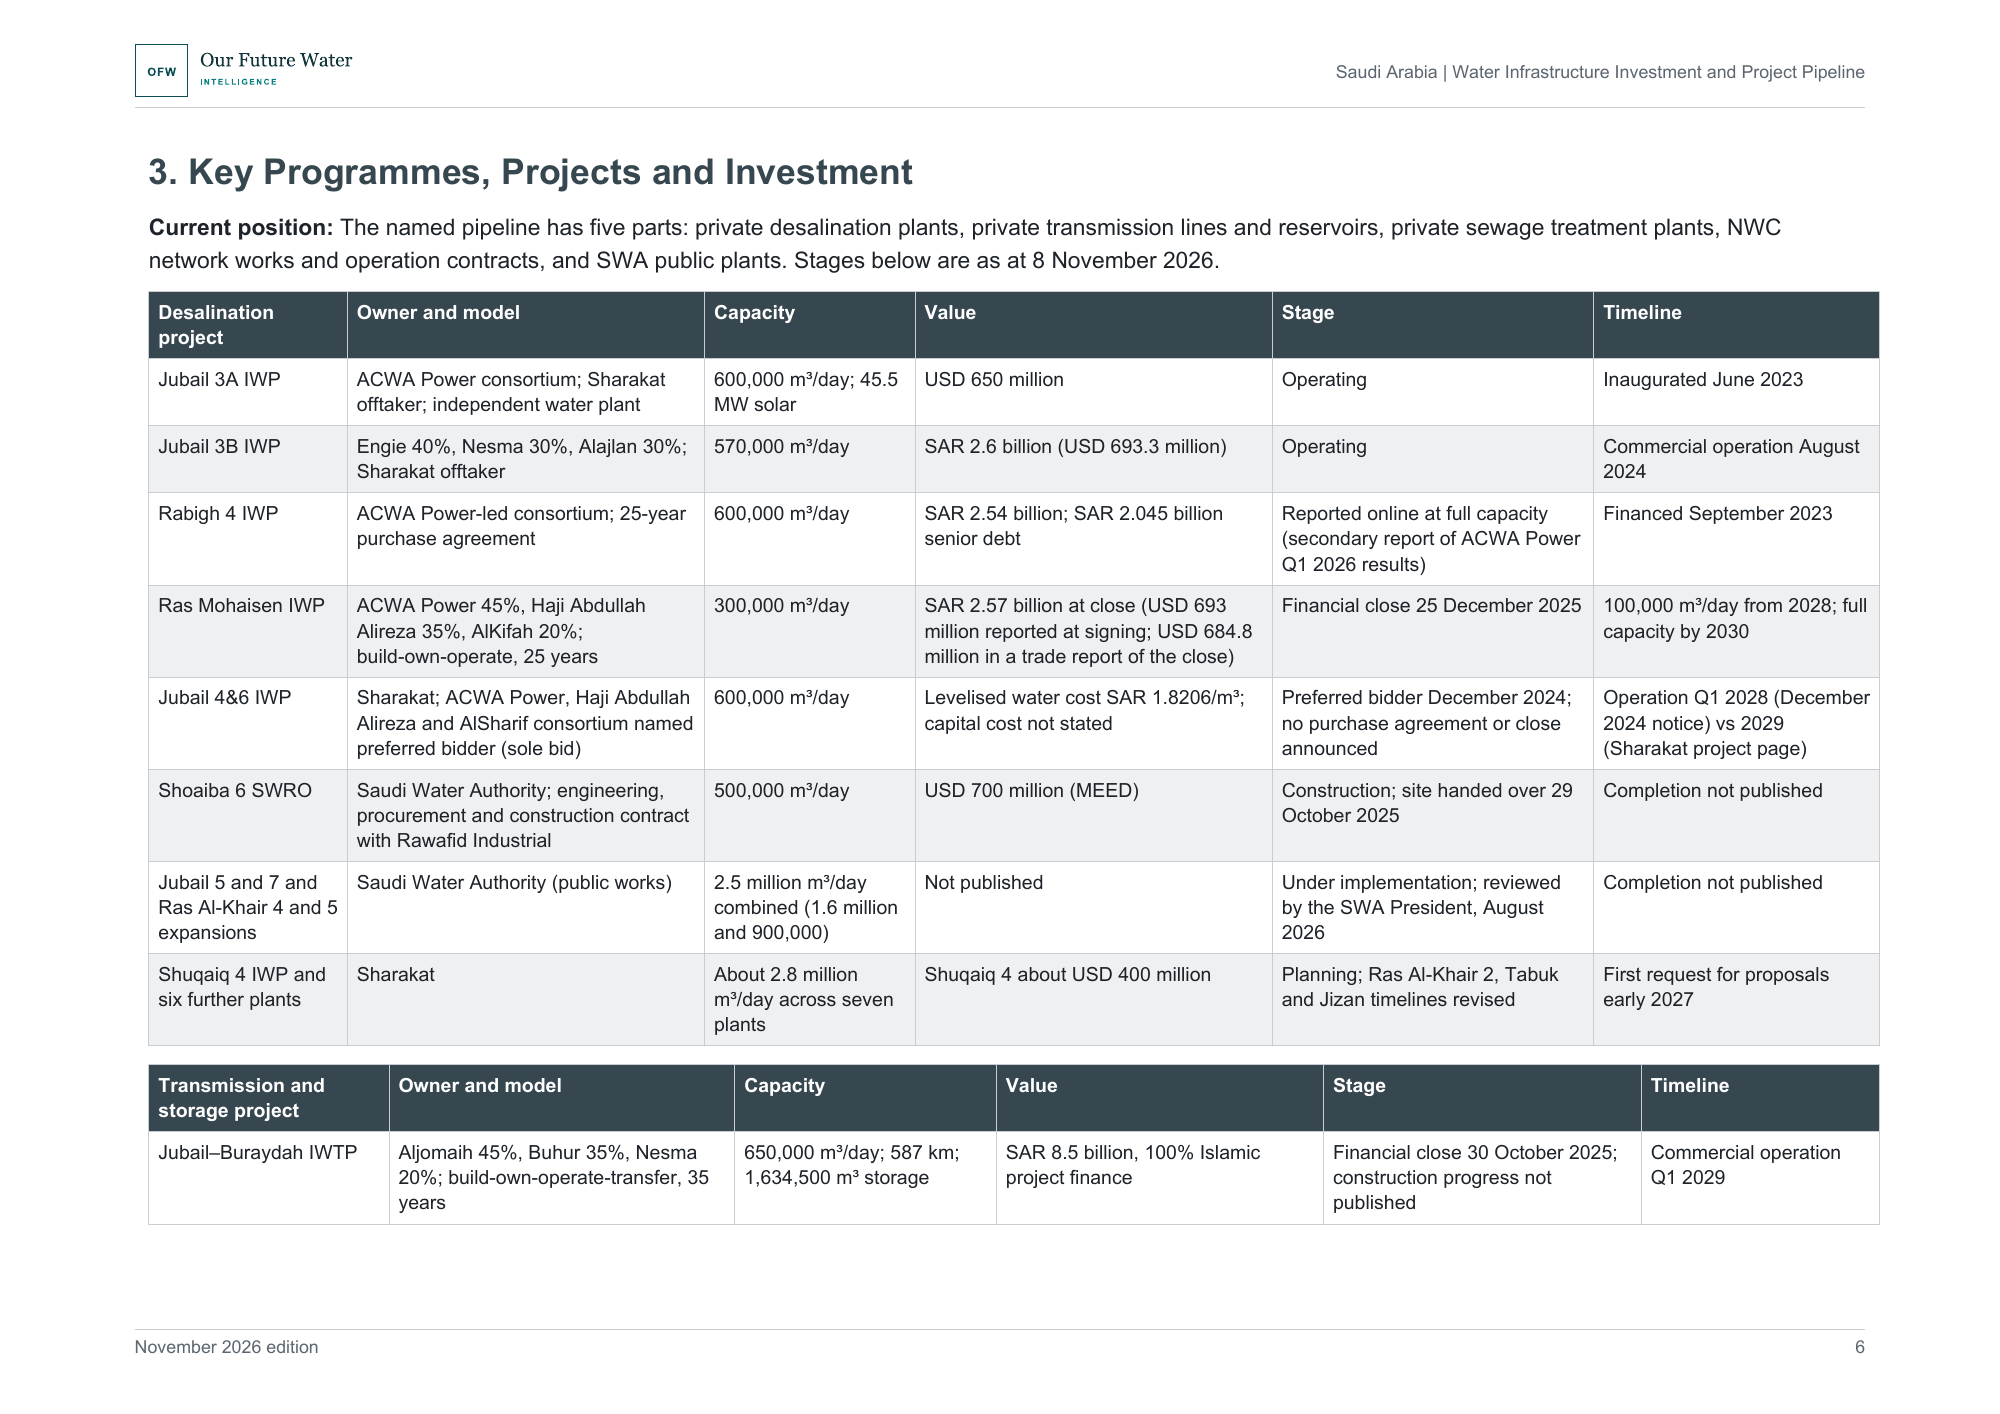
Section 3: Saudi desalination, transmission and storage projects, with owner, capacity, value, stage and timeline
06
Included
What you receive
The complete PDF report: 14 pages, 9 sections, 13 tables and a register of 38 sources.
This edition
November 2026, First edition.
07
Evidence & method
Evidence and method
The report draws on Sharakat's project portfolio and announcements, ministry and Saudi Water Authority statements, NWC's operating and project disclosures, project financing announcements and MEED's procurement reporting. Project stages were checked on 8 November 2026.
Sources
38 sources, listed in the report's source register. Evidence current to 8 November 2026. Principal data periods: Project stages and procurement as at 8 November 2026; Sharakat portfolio June 2026; NWC capital works 2024 to H1 2026; contract awards H1 2025 to September 2026. Currency: Saudi riyal (SAR); US dollars (USD) where sources use them (SAR 3.75 = USD 1)..
Evidence boundaries
This report uses authoritative source material available at the stated research cutoff. It distinguishes published facts, calculated values and analytical interpretation. No independent modelling is performed. Forward-looking analysis reflects published plans, documented trends and stated uncertainties. It does not constitute legal, financial, investment or engineering advice.
08
Lead analyst
Robert C. Brears
Founder, Our Future Water Intelligence
Robert C. Brears is a water-security specialist and author whose work examines utility governance, infrastructure investment, climate resilience and long-term water-system change for executive and policy audiences.
- Decision-focused utility intelligence
- Published water-policy author
- Evidence-grounded system analysis
09
Buyer FAQs
Before you purchase
Who can use the report?
Licensed for internal use within one purchasing organization. The PDF and its contents may be shared with colleagues within that organization. External redistribution, resale and public publication are prohibited without permission.
How is the report delivered?
The PDF is available to download immediately after confirmed payment, through our secure delivery system.
Can my organization buy wider access?
Institutional purchasing: For invoice enquiries, multi-organization licensing or broader access requirements, contact Our Future Water Intelligence.
10
Water Infrastructure Investment and Project Pipeline in Saudi Arabia
- Format
- Length
- 14 pages
- Edition
- November 2026, First edition
- Price
- USD 249
11
Report details
Publication details
- Publisher
- Our Future Water Intelligence
- Report family
- Insight Brief
- Edition
- November 2026, First edition
- Format
- Length
- 14 pages
- Reference
- OFW_EXT_WATER_INFRASTRUCTURE_INVESTMENT_AND_PROJECT_PIPELINE_IN_SAUDI_ARABIA_4664988fae60
- Evidence current to
- 8 November 2026
14
Explore this report family
More Water Infrastructure Investment and Project Pipeline briefs
Explore the same report family covering other countries.
Water Infrastructure Investment and Project Pipeline in Bahrain
- Geography
- Bahrain
- Edition
- November 2026, First edition
- Length
- 12 pages
Water Infrastructure Investment and Project Pipeline in Denmark
- Geography
- Denmark
- Edition
- November 2026, First edition
- Length
- 11 pages
Water Infrastructure Investment and Project Pipeline in Germany
- Geography
- Germany
- Edition
- November 2026, First edition
- Length
- 12 pages